Luxury Detached Homes
Previously, the $2.5m-3.0m range was one we were watching - it has been hot through spring/summer - but the stats don't fully justify the headlines.
In the last month, the $2.0-$2.5m segment has heated up: The Inner City has seen 12 sales in the last month as compared to only 4 in July - a trend we're very interested in watching, as confidence may be spreading down market from thought leaders, and inventory gradually evaporates.
On paper, at least, the Inner City $2.0-$3.0m market has become a seller's market - without more inventory, if sales continue apace, we could begin to see more upward pressure on prices. Our anecdotal experience on the ground supports the idea that it's an increasingly competitive market.
Luxury Apartments
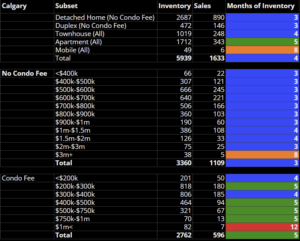
Conversely, you will notice that $1m+ apartments are seeing red - 12 months of inventory (MOI), as compared to around 4 MOI over the summer. We were surprised that this segment hadn't yet really adjusted down like the broader condo market, and it appears to be playing catch-up. Well - I suppose "catch-down". We're witnessing lots of heavy price reductions in some of the best buildings - listings priced significantly lower than comparable sales, and still not selling. Anecdotally, sales drop off over the $800k or so mark.
Broader Market
Key points:
- The detached market is very stable. Inventory is tighter than it was this time last year (as a result of reasonably adjusted sales stabilizing and the rate of new listings YoY being down). Areas away from new construction sometimes feel tight.
- The condo market has grown even weaker over the summer, and that trend is continuing this month. There are 5 months of inventory (MOI) with prices falling. The difference between 3 MOI (detached) versus 5 MOI might seem small, but it's night and day on the ground - discounts, list price changes etc. Sellers often need to be very committed, and in this market, many of them really are.
Outlook
Looking ahead, there are a few things pulling segments in different directions:
Positive: The recent pipeline news is encouraging, although we've heard plenty of pipeline announcements over the years - some end up with steel in the ground, and others don't.
Negative: Rising bond yields have been pushing mortgage rates up, while tariff uncertainty continues to hang over the broader economy, perhaps less so here in Calgary. Alberta separation is also coming up in conversation, but so far it's little more than passing comments from our buyers & sellers.
On balance, barring a major global event, we think the optimism surrounding Alberta's oil and gas sector will outweigh these other concerns, and we're generally positive about the outlook.
If we were to guess, in the absence of new news, we might expect the following future:
1) The strength we're seeing in luxury detached homes could spread into the $1.5m-$2.0m range or even to $1.0m-$1.5m, particularly in the Inner City. Buyers at the higher end tend to be more cash- and stock-heavy, and therefore more influenced by confidence in Alberta's oil and gas sector than by rising mortgage rates.
2) Continued balance in the broader detached market, with conditions gradually shifting towards sellers in more enduring areas away from new construction.
3) A continued buyer's market for apartments, with rents under pressure as more purpose-built rentals come on stream - still sidelining investors and even first-time buyers, unless prices are extremely attractive.
#1 Agent Reports from Across Canada This month's Insider's Market Report contains a couple of dozen individual reports you can read.
Tap HERE to catch up on how different markets are reacting to all the economic news.